
Quick Links:
Applying for a buy-to-let mortgage can feel daunting, especially for first-time landlords. With expert support, the process becomes much easier. Here’s a comprehensive guide to securing a buy-to-let mortgage.
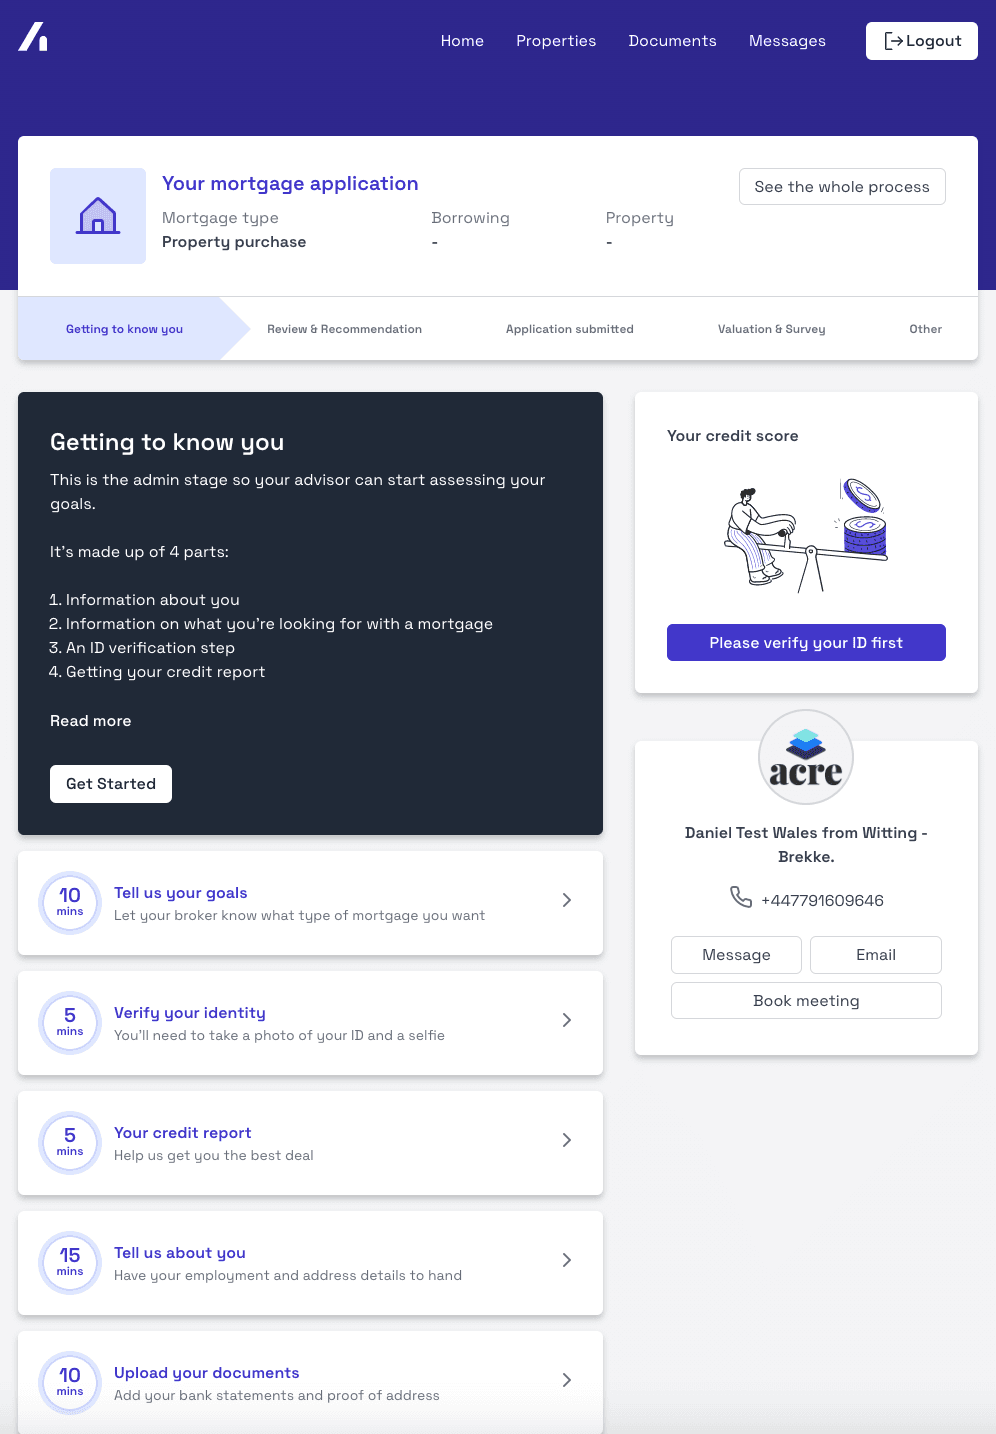
1. First Chat and Planning
It starts with understanding your goals. At HTG Mortgages, we’ll discuss your:
Financial situation, including savings and credit history.
Investment goals, whether it’s rental income or long-term capital growth.
2. Eligibility Requirements
Buy-to-let lenders have specific criteria:
- Deposit: You’ll typically need at least 20-25%.
- Rental Income: Lenders usually expect rental income to cover 125-145% of the mortgage payments.
- Creditworthiness: A good credit history is vital, but some lenders won’t look into your personal income.
3. Mortgage Options
We’ll help you explore whole-of-market products, including:
Fixed-Rate Mortgages: Ideal for predictable monthly payments.
Interest-Only Mortgages: Lower monthly costs with a lump sum due at the end of the term.
4. Application and Documentation
Once we’ve found the right product, we’ll handle the paperwork, including proof of income, credit checks, and property details.
Who Can Get a Buy-to-Let Mortgage?
Buy-to-let mortgages are generally available to anyone looking to invest in property and rent it out. However, lenders will have specific criteria you must meet, including:
Minimum Income: Some lenders require you to earn a minimum personal income.
Age Limits: Many lenders have age limits for buy-to-let mortgages, typically ranging between 18 and 75. Some will allow the mortgage to continue into retirement, but this depends on individual circumstances.
5. Property Valuation and Lender Approval
The lender will assess the property to ensure it’s a viable investment. Upon approval, you’ll receive a formal mortgage offer.
6. Finalising the Purchase
With your mortgage secured, you can proceed with the property purchase. At this stage, we continue to support you by offering advice on the next steps, including insurance and landlord responsibilities.
Why Consider a Buy-to-Let Mortgage?
Despite the risks, buy-to-let can be a smart financial move if handled carefully. Many investors see property as a tangible asset that can provide both a regular income and capital growth over time. With the right property in the right location, your rental income could not only cover your mortgage payments but also give you a profit.
Here’s why some people opt for a buy-to-let mortgage:
Potential for Long-Term Returns: As property prices generally rise over time, there’s the potential for long-term capital growth in addition to rental income.
Diversification of Investments: Investing in property can be a good way to diversify your investment portfolio, reducing reliance on traditional stock markets.
Final Thoughts
At HTG Mortgages, we specialise in guiding landlords through the buy-to-let mortgage process. From the first chat to securing the right mortgage, we’re here to make your property investment smooth and successful. And when your first fixed rate comes to an end, our guide to how a buy to let remortgage works covers the next step.
Buying at auction compresses this whole process into about 28 days, which I cover separately in my auction property mortgage guide.
Book a Free Chat
Ready to take the first step? Get expert advice tailored to you. No obligations, no pressure. Fill out the form and let’s make it happen!
