
Written by Harry Goodliffe
Director & Mortgage Adviser, HTG Mortgages · FCA Authorised (1017945)
CeMAP Qualified · Featured in National Press · South England Prestige Awards 2026/27 winner

HTG Mortgages
We work closely with our sister company HTG Property Group to support landlords from financing through to letting and ongoing property management. Whether you are purchasing your first rental property or expanding an existing portfolio, we can help.
Unbeatable service – personal, friendly, and focused entirely on you.
Whole-of-market choice – access to every first-charge mortgage out there.
Here when you need us, Monday to Friday 8am to 5pm and Saturday 8am to 1pm.
Investing in property can be a powerful way to build long-term income, but arranging the right buy-to-let mortgage is only one part of the process.
We work closely with our sister company, HTG Property Group, to support landlords from the financing stage through to letting and ongoing property management.
Once your rental property mortgage is in place, HTG Property Group can help manage the practical side of being a landlord.
Their team handles tenant sourcing, tenancy agreements, rent collection, and day-to-day maintenance. This makes it easier to focus on growing your property portfolio without the time-consuming admin.
Whether you are purchasing your first rental property or expanding an existing portfolio, having the right mortgage advice and property management support can make the process far simpler.
HTG Mortgages and HTG Property Group are separate companies with the same directors. While they work closely together, they operate independently and are not legally linked entities.
Ready to take the first step? Get expert advice tailored to you. No obligations and no pressure. Fill out the form and let’s make it happen!
Most buy-to-let mortgages require a larger deposit than residential mortgages. In many cases, lenders expect a minimum deposit of around 20-25% of the property value. A larger deposit can sometimes help secure more competitive mortgage rates.
Lenders also look closely at the expected rental income from the property. In many cases, the rent must cover around 125-145% of the mortgage repayments, although the exact requirement varies between lenders.
Some lenders may also expect landlords to have a minimum personal income, even though the mortgage is supported by rental income. Credit history, existing borrowing, and experience as a landlord can also influence the options available.
Working with an experienced landlord mortgage broker can help identify lenders that suit your situation and investment plans
**HTG Mortgages and HTG Property Group are separate companies with the same directors. While they work closely together, they operate independently and are not legally linked entities.
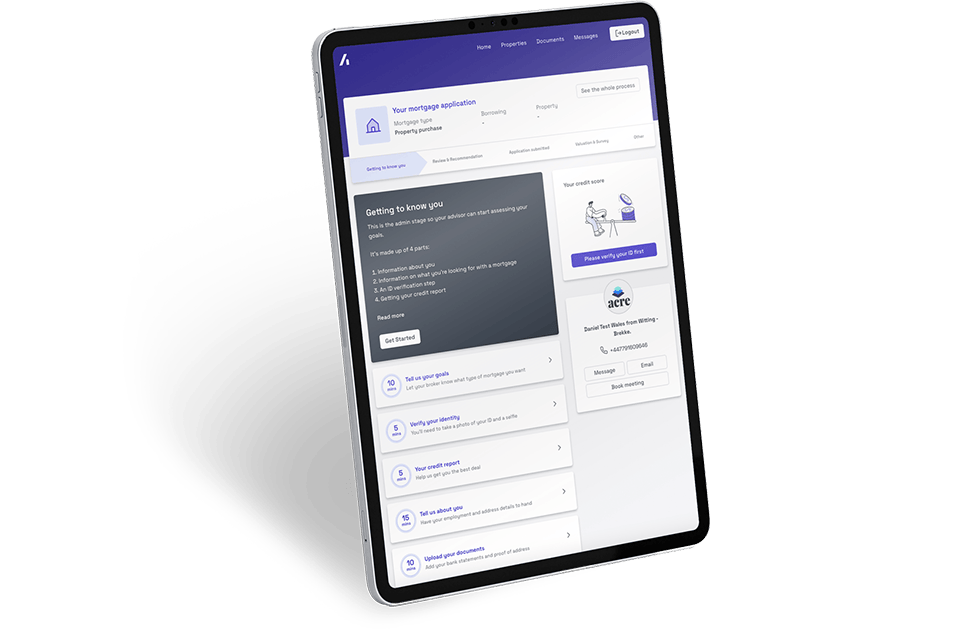
Our experienced advisers are here to guide you – whether you’re buying your first home, remortgaging, or protecting your property and lifestyle. We’ll save you time and hassle by comparing deals from across the market for you.
Most buy to let pages in this county tell you rental demand is strong and stop there. That is not much help when you are deciding whether to offer on something. So I ran the test lenders actually apply across all sixteen local authorities I cover, and here is what came back.
The two that pass are Portsmouth, which clears with real room to spare and has the strongest yield in the county, and Southampton, which clears more narrowly. Everywhere else needs one of the levers below.
A limited company is assessed against an easier cover ratio than a higher rate taxpayer borrowing personally, and a larger deposit shrinks the loan the rent has to cover. Combine both and more than half the county passes. Company rates are usually higher, so the easier test is not automatically the cheaper mortgage.
The weakest yields sit in the places people most want to live, Winchester among them. Knowing that before you offer is worth more than finding out at valuation. I would rather tell you a property does not stack up than arrange you a mortgage you regret.
Figures calculated from HM Land Registry and ONS UK House Price Index data (May 2026) and ONS Price Index of Private Rents data (June 2026), at 75% loan to value and a 5.5% stress rate, using a 145% rental cover ratio for a higher rate taxpayer borrowing personally and 125% for a limited company. The nine of sixteen figure assumes a limited company at 60% loan to value. These are averages for each local authority, not a valuation of any particular property. Every lender uses its own surveyor's rent assessment, its own cover ratio and its own stress rate. Correct as at August 2026.
If you are just getting started: how to become a landlord, what counts as a good rental yield and student buy to let.
Figures are for illustration only, based on the assumptions and sources shown, and are not a quote or a guarantee of what you can borrow or what a lender will accept. Lender criteria and rates change often. Read the full important information.